

Second Job Tax in Australia: Why Your Second Job Isn’t Really Taxed More

All states and territories in Australia
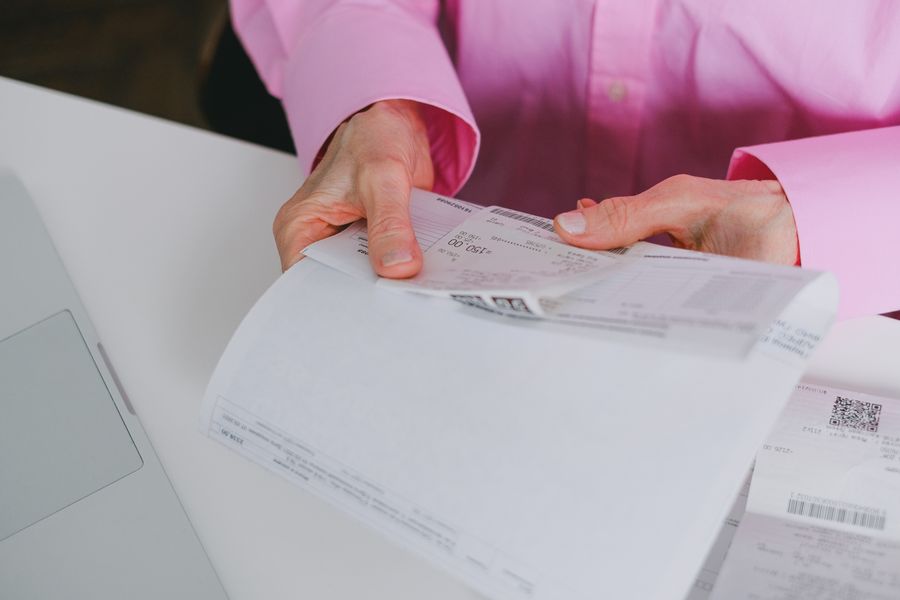
Compare two payslips and it looks obvious: your main job pays $1,538 a fortnight and roughly $126 comes out in tax, while your second job pays $769 — half as much — yet nearly the same amount disappears. It feels like a penalty rate for working twice. It isn’t. There is no second job tax in Australia, and once you see how withholding works, the payslips make sense.
There is no second job tax rate
The ATO does not tax your jobs separately: when you lodge your return, all your income is added together and taxed once, at the standard resident tax rates: for 2026–27, no tax on the first $18,200, then 15c per dollar up to $45,000, 30c to $135,000, 37c to $190,000, and 45c above that. Each rate applies only to the slice of income in its bracket — so a dollar earned on a Saturday shift is taxed exactly like a dollar earned on a Tuesday. Only your yearly total matters.
The tax-free threshold is where the illusion starts
As a resident, your first $18,200 each year is tax-free. You claim that threshold through one payer only — usually the job that pays you the most. Every other payer withholds tax from the first dollar you earn, using the no-threshold rates. That is the entire mystery: your main job’s withholding starts gently because the threshold is baked in, while your second job is taxed from dollar one, so a far bigger share of a smaller pay vanishes.
Claiming the threshold twice. If you claim it from two payers, each one leaves $18,200 of your pay untaxed through the year. Too little is withheld overall, and the shortfall arrives as a tax bill when you lodge. (One exception: if your total income will be $18,200 or less, the ATO allows claiming it from more than one payer.)
Not claiming it where you should. Leave the threshold off your main job and you are over-withheld all year: a bigger refund later, but smaller pays meanwhile.
A worked example: same income, same tax
Meet Alex. Scenario one: one job paying $60,000. On the 2026–27 rates, the first $18,200 is tax-free, the next $26,800 is taxed at 15c ($4,020), and the remaining $15,000 at 30c ($4,500) — income tax of $8,520, plus the 2% Medicare levy of $1,200. That is $9,720 all up, before offsets.
In the second scenario, Alex earns the same $60,000 split across a $40,000 main job and a $20,000 second job. The tax is identical: $9,720. Only the timing changes. At the main job, where Alex claims the threshold, withholding on a $1,538 fortnight comes to roughly $126. At the second job, where tax runs from the first dollar, a $769 fortnight loses roughly $115 straight away — nearly as much tax on half the pay. Nothing extra was charged; it was just collected earlier and harder, and any gap against the $9,720 is squared up in the return, as a refund or a bill.
How to fix your withholding
Check who you claim the threshold from — it should be one payer, normally the highest. To change it, give the relevant employer a completed Withholding declaration form rather than waiting for a bill. Irregular second income? You can also ask an employer to withhold a little extra each pay. And when tax time comes, having your records straight is half the battle — our EOFY receipt rescue shows how to get them in order before 30 June.
Got a HELP or HECS debt?
A study loan makes a second job feel heavier again. Once your total repayment income passes the minimum threshold — $69,528 for 2026–27 — compulsory repayments are worked out on your combined income from all jobs, at marginal rates. Each employer only withholds extra towards the repayment if it knows about the loan, and each one estimates based on its own pay alone — so a second job can quietly push your total over the threshold and leave a top-up to pay at tax time. Tell every employer about the loan on your withholding declaration.
The Medicare levy rides along
On top of income tax, most residents pay the Medicare levy at 2% of taxable income — again on your total, not per job, as the ATO notes alongside its resident tax rates. Wage withholding usually includes an amount for it — one more reason the second payslip looks thin.
If the second income is gig or ABN work
Work billed under an ABN — delivery driving, freelancing, a weekend market stall — is different: nobody withholds anything, so every dollar lands in your account and the tax is entirely your problem at lodgement. The ATO suggests setting tax aside as you go, or prepaying through PAYG instalments, to avoid one lump-sum bill. It is taxed as sole trader income, so deductions enter the picture — see our guide to sole trader tax deductions in Australia for what you can claim. If that ABN income grows, there’s also the $75,000 GST question — the turnover line where GST registration becomes compulsory.
How Lemon fits
Two payslips are hard to read in isolation; the year view is what counts. Lemon lets you log each job’s pay as it lands and watch your combined income build in one place, so you know which bracket your total is heading for — and whether your withholding is keeping up — long before tax time.
This article is general information, not tax advice. For your specific situation, talk to an accountant or tax agent.
Download Lemon free on the App Store or Google Play — log the pay from both jobs in one place so you always know what you’ve actually earned across the year.
About this author
Contribute your article